
Personal loans
Customized financing to consolidate high-interest debt and unlock financial flexibility.
About BHG
Programs
Can You Consolidate Personal Loans?
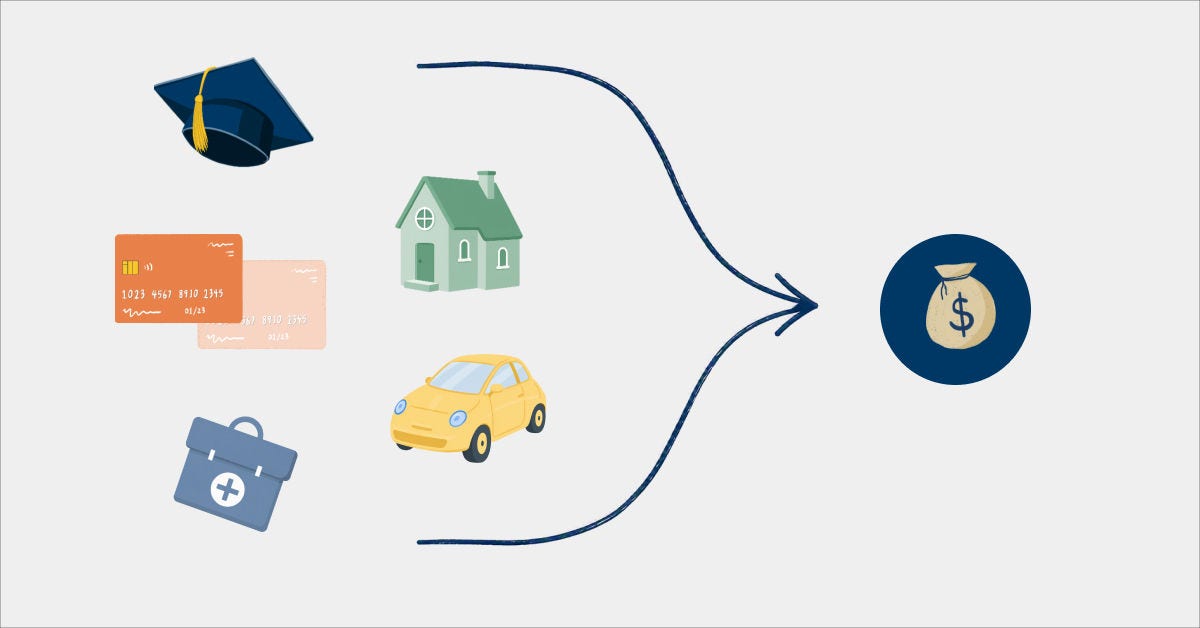
Juggling different bills, due dates, and interest rates can feel like a never-ending cycle, leaving you stressed and overwhelmed. If you find yourself in this situation, a debt consolidation loan could be a helpful tool for regaining control of your finances.
Yes—you can consolidate personal loans. A debt consolidation loan allows you to combine multiple existing personal loans (and other eligible debts like credit cards) into one new loan with a single monthly payment.
Below, we'll explain how consolidating loans can help you manage and eliminate debt efficiently, setting you on the path to better financial balance.
Key Considerations
- Debt consolidation loans combine multiple debts into one manageable monthly payment, simplifying your finances.
- Consolidation loans can potentially lower your interest rate.
- Understanding how consolidation may positively affect your credit score can help you make decisions that support your long-term financial health.
Can you consolidate personal loans?
You can consolidate personal loans with a debt consolidation loan—a type of personal loan that combines multiple existing debts into one loan with a fixed monthly payment. This may include personal loans with different interest rates, as well as other high‑interest balances such as credit cards.
Consolidating can be a smart option if you’re looking to streamline payments, reduce mental and financial strain, and potentially save money on interest—especially if your current loans carry higher APRs.
How can you consolidate personal loans?
Consolidating personal loans is a structured but straightforward process. Here’s how it typically works:
- Review your current debts: List your existing personal loans, credit cards, and other eligible balances, along with their interest rates and monthly payments. Determine the loan amount you need to borrow to refinance your existing debts.
- Apply for a personal loan for debt consolidation: Apply for a consolidation loan with your preferred lender or financial institution. If approved, you'll get a lump sum designed to cover some or all of your existing balances.
- Pay off existing debts: The funds are used to pay off your personal loans, credit cards, or other eligible obligations. Many borrowers use consolidation loans to pay down high credit card balances, which can help lower credit utilization and support credit score improvement.
- Repay one fixed monthly payment: You’ll make a single, predictable payment to your new provider over a set term, often at a fixed interest rate.
While balance transfer credit cards are another consolidation option, they often come with transfer limits and short promotional periods. For borrowers with larger balances or longer‑term planning needs, a personal loan can offer more stability.
FYI: Personal loans for debt consolidation through BHG Financial are available in amounts up to $250,0001 with extended, flexible terms of up to 10 years.1,2
See your offer † real fast
Just a few easy steps to get prequalified!
† This is not a guaranteed offer of credit and is subject to credit approval.
What types of debt can you consolidate?
All types of unsecured debt, as well as certain types of secured debt, are often eligible for debt consolidation. Generally, people opt to merge multiple loans into one when they have multiple types of high-interest debt and they are looking for easier debt management.
Here's a look at some of the types of debt you can consolidate:
- Other personal loans
- Credit cards with high balances
- Education loans
- Medical bills
What are the pros and cons of consolidating personal loans?
Pros of personal loan consolidation:
- One monthly payment is easier to manage than multiple
- Potentially lower rates than your existing debts, saving you money
- Fixed-rate loans offer consistent monthly payments, making budgeting easier
- Extended terms may help lower your monthly payment, improving cash flow
- Paying off high credit card balances can help improve your credit utilization ratio, and in turn, positively impact your credit score
Cons of personal loan consolidation:
- If the new loan has a longer repayment term, you could pay more interest over time
- Typically, only prime borrowers secure the lowest interest rates on consolidation loans
- Consolidation loans may come with origination fees
- Consolidation doesn’t resolve underlying financial problems. If you don’t adjust your spending habits, you could accumulate debt again.
One of the biggest benefits of a debt consolidation loan is its simplicity. Managing one predictable payment reduces the risk of missed due dates, late fees, and unnecessary credit damage.
Consolidating generally only makes sense if you can secure a lower interest rate than your existing debts, allowing you to save interest over time and allocate a larger portion of your monthly payment to the principal.
Making on-time payments on your new loan can also help establish a positive credit history.
A solid budget and financial discipline can help ensure the impact of loan consolidation on your credit is positive. In fact, most borrowers who consolidate debt through BHG Financial improve their FICO score by 30 points or more within a few months of funding.*
With a stronger credit score and better borrowing power, you could save money on other future purchases, like mortgages and cars, which may also have lower rates.
That said, it’s important to consider the costs of borrowing before taking out the loan to ensure it’s something you can afford. Debt consolidation loans may come with upfront fees, such as origination fees. These can add to the overall cost of the loan, so it's important to understand all charges before you commit.
How does BHG Financial support consolidating personal loans?
BHG Financial understands the stress six-figure earners face when managing multiple types of debt and selecting the right financing solution. Personal loans for debt consolidation through BHG are specifically designed to consolidate large amounts of existing debt, including existing personal loans.
- Flexible repayment terms: Personal loans through BHG come with extended repayment terms of up to 10 years.1,2 Our loan experts will work with you to establish repayment terms that fit your budget and help keep payments manageable.
- Higher loan amounts: Most providers offer personal loans for debt consolidation up to $100,000, but BHG financing solutions extend up to $250,000.1
- Simpler finances: Consolidating multiple balances into one fixed payment can reduce financial noise, improve predictability, and make it easier to plan ahead with confidence.
Our application process is fast and efficient, allowing you to receive the funds you need quickly. You can prequalify online in minutes, and it will not impact your credit score.3
Ready to see how BHG can help you consolidate multiple loans? Use our quick and easy payment estimator to get your personalized loan estimate in just seconds.4
Check my rate
See your offer † real fast
Just a few easy steps to get prequalified!
† This is not a guaranteed offer of credit and is subject to credit approval.
Frequently asked questions (FAQs)
Is consolidating personal loans a good idea?
Consolidating personal loans can be a good idea if it simplifies your finances, lowers your interest rate, or improves monthly cash flow. It’s most effective when paired with disciplined repayment habits and a clear plan to avoid accumulating new debt.
How can you get out of personal loan debt?
You can get out of personal loan debt by consolidating your existing loans into a more advantageous structure. Strategies may include consolidating high‑interest balances, setting up automatic payments, and directing extra funds toward principal when possible.
How much can I save by consolidating my loans?
The amount you can save by consolidating your loans depends on the interest rate of your new consolidation loan and the repayment term you choose. If your new loan has a significantly lower interest rate than your existing debt, you can save a considerable amount on interest charges over time. BHG allows you to prequalify and compare loan offers without affecting your credit score.3
Can I consolidate both personal loans and credit card debt?
Absolutely! A personal loan for debt consolidation is commonly used to merge various types of unsecured debts, like personal loans, credit card debts, and medical bills, into one payment.
What’s the difference between consolidation and refinancing?
While both consolidation and refinancing are commonly used to potentially secure better rates or loan terms, they are not quite the same. Consolidation involves combining multiple existing debts into a single new loan, typically to simplify payments and potentially secure a lower interest rate. Refinancing typically involves taking out a new loan to replace a single existing loan—like when you refinance your mortgage to get a lower interest rate or a shorter loan term.
Is there a limit to how many loans I can combine?
You can generally combine as many eligible unsecured debts as you wish, as long as the total amount you need to borrow fits within the provider’s loan limits, and you qualify based on your creditworthiness and income. BHG Financial offers access to large loans up to $250,000,1 which can accommodate a significant number of existing debts for those with substantial income.
Not all solutions, loan amounts, rates or terms are available in all states.
*Based on internal data, most BHG debt consolidation borrowers may improve their FICO® score by 40+ points within 2 months. Credit scores depend on many factors and individual results may vary based on personal spending habits.
1 Terms subject to credit approval upon completion of an application. Loan sizes, interest rates, and loan terms vary based on the applicant's credit profile. Not all applicants will qualify for the lowest rate.
2 Personal Loan Repayment Example: A $60,000 personal loan with a 7-year term and an APR of 17.06% would require 84 monthly payments of $1,191.38.
3 There is no impact on your credit for applying. For personal loans, a complete credit history, which will appear as an inquiry on your credit report, will be performed upon acceptance and funding of the loan and may impact your credit.
4 This is not a guaranteed offer of credit and is subject to credit approval.
No application fees, commitment, or impact on personal credit to estimate your payment.
Consumer loans funded by Pinnacle Bank, a Tennessee bank, or County Bank. Equal Housing Lenders. 
For California Residents: Personal loans made or arranged pursuant to a California Financing Law license - Number 603G493.

Bankers Healthcare Group, LLC d/b/a BHG Financial NMLS ID# 2040829