Personal loans
Customized financing to consolidate high-interest debt and unlock financial flexibility.
WAYS TO USE YOUR LOAN
Resources
Guides, insights, and research – explore our latest articles.
About BHG
Programs
How Consolidating Debt Can Free Up Cash for Bigger Goals
If you’re a successful professional with high-interest credit card debt, hitting your financial milestones can feel difficult. Debt payments can compete with priorities like retirement savings, home renovations, travel, or funding your child's education.
Here’s the good news: debt consolidation offers a way to simplify repayment, free up cash flow, and redirect your income toward what matters most. By using a personal loan for goals instead of watching money vanish into compounding and variable interest, you create financial breathing room and a clear path forward.
In this article, we cover how a personal loan for debt consolidation can be a powerful tool for six-figure earners to improve cash flow and overall financial health.
Create financial breathing room
With a low, fixed personal loan monthly payment
How consolidating debt can improve monthly cash flow
Debt consolidation can positively affect your monthly cash flow, freeing up funds for the money moves that matter to you.
Whether you’re consolidating credit cards, personal loans, or medical bills, here are the ways it helps you create more breathing room in your budget.
Lower monthly payments with a fixed rate
By consolidating multiple debts into one fixed-rate personal loan, you reduce the number of payments you need to make each month and simplify your finances. Because repayment can be spread over a longer loan term, you can often lower the amount you owe monthly and ease the pressure on your budget.
Let’s assume that you owe $50,000 across four credit cards with an average 23% APR (variable), and those four payments total $1,000 per month. If you consolidate that credit card debt into a 10-year personal loan with a 12% fixed APR, your monthly payment could drop to around $717, leaving you with $283 extra each month for other goals.
Less interest can mean more liquidity
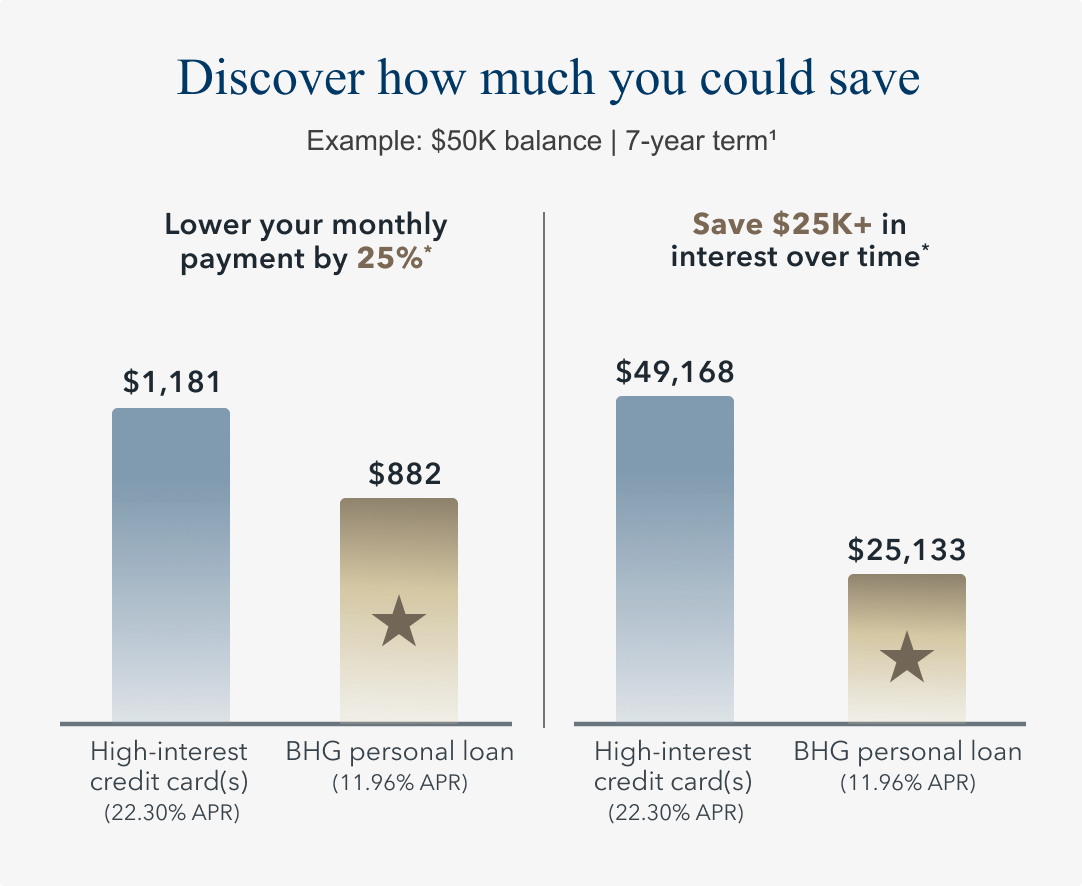
The less you spend on interest, the more cash remains available for other priorities. For example, if you're carrying $50,000 across multiple credit cards with APRs between 18% and 25%, consolidating into a lower-rate fixed loan could save hundreds each month and thousands in interest over time.
Advertised rates are subject to change without notice.
Monthly payment is a representative example and for illustrative purposes only.
* Potential savings based off comparing repayment of a $50,000 balance over 7 years on both a credit card with a minimum monthly payment of $1,181 and APR of 22.30% (average consumer credit card APR per The Federal Reserve as of 04/01/26), with the assumption no additional draws on the line are made during this time; and a BHG Personal Loan with a minimum monthly payment of $882 and minimum available APR for a 7-year term, which is 11.96% as of 05/05/26 and includes an origination fee.
Fixed rates also make planning easier. Unlike variable-rate debt, which can fluctuate based on what happens in the market, fixed-rate debt stays the same throughout the loan term. This protects you from unpredictability, allowing you to more confidently budget money for future needs and plans.
Freeing up cash flow for wealth-building moves
With the additional cash flow you gain through debt consolidation, you can boost your emergency fund, maximize your 401(k) contributions, or expand your real estate portfolio. All these strategies may improve your long-term wealth. You could also consider making major home renovations or additions you’ve held off on, possibly with the help of a home improvement loan to preserve your liquidity.
Additionally, you’ll benefit from a clear payoff date. Knowing when your debt will be paid off makes it easier to plan how you’ll build wealth moving forward. As a bonus, paying down revolving balances can boost your credit score by lowering utilization and strengthening your credit profile over time.
Most borrowers who consolidate debt through BHG improve their FICO score by 40 points or more within a few months of funding.*
Cash flow before and after consolidating debt: An example
|
Monthly cash flow |
Amount before consolidation |
Amount after consolidation |
|---|---|---|
|
Gross monthly income |
$16,660 |
$16,660 |
|
Mortgage payment |
$2,900 |
$2,900 |
|
Personal loan payments (30,000 balance) |
~$1,000 |
— |
|
Lifestyle and other fixed expenses |
$6,000 |
$6,000 |
|
Credit card payments (50,000 balance) |
$1,000 |
— |
|
Consolidation loan payment |
— |
~$1,140 |
|
Remaining before taxes, insurance, and other deductions |
$5,760 |
$6,620 (+860) |
A household earning $200,000 annually brings in roughly $16,660 per month before taxes. With $2,900 going toward a mortgage, $1,000 toward personal loan payments, $6,000 in lifestyle and fixed expenses, and about $1,000 in monthly credit card payments, they could be committing nearly $10,900 each month before accounting for taxes, insurance, retirement contributions, or unexpected costs.
But if that $80,000 in total personal loan and credit card debt is consolidated into a 10-year, fixed-rate consolidation loan, the debt payments could fall from $2,000 per month to about $1,140.
That change puts approximately $860 back into monthly cash flow, creating more flexibility to build an emergency fund, increase retirement contributions, invest for future goals, or accelerate debt repayment whenever their financial situation allows revolving balances can boost your credit score by lowering utilization and strengthen your credit profile over time.
When debt consolidation makes sense for six-figure earners who need to improve cash flow
Debt consolidation can make sense for high earners facing financial friction in various situations, from growing revolving balances to end-of-month cash flow strains. Let’s look at how it might help in four scenarios.
If you’re juggling multiple debt payments each month
Even if you can afford it, multiple debt payments can complicate your finances. You might struggle to track all the due dates, and some may not align with your cash inflows. If you’re in this situation, debt consolidation can reduce stress, leaving you with one monthly payment that’s manageable and aligned with your cash flow.
If you don’t have the cash you need at the end of the month
Large debt payments can strain cash flow even for high earners. When too much income goes toward existing debt, it becomes harder to save, cover unexpected expenses, or pursue financial goals.
Debt consolidation may create additional flexibility by lowering your monthly payment and make monthly budgeting less frustrating.
If you don’t want to liquidate investments to pay off credit cards
While paying off high-interest credit card debt is a smart wealth-building strategy, liquidating investments to pay off debt may trigger taxes, reduce liquidity, and limit future growth potential.
Debt consolidation may allow you to address costly debt while keeping invested assets intact. For some borrowers, maintaining investment exposure while reducing interest costs can be a more attractive long-term strategy.
If interest keeps compounding on outstanding balances
When interest compounds, especially at a high rate, you might feel like your minimum monthly payments barely move the needle. Consolidating into a fixed-rate loan can provide a lower rate, a predictable payment, and a defined payoff timeline.
To evaluate whether consolidation makes sense, compare your current payments and average APR with the payment and interest rate available through a consolidation loan.
A debt consolidation loan through BHG Financial can boost your cash flow
Earning six figures doesn't make a cash crunch feel any less real. When a big chunk of your monthly income is going toward five different minimum payments, it doesn't matter what your W-2 says. You're lying awake doing math, feeling the squeeze between your ambitions and your obligations. That pressure is valid and common among high earners.
Your income is an asset, and the right loan structure can put it to work instead of letting it get absorbed by scattered high-interest debt. Consolidating your debt into a single personal loan through BHG Financial replaces multiple payments with one fixed monthly payment at a predictable rate for the life of the loan.
With terms up to 10 years1,2, you can stretch payments to lower your monthly amount, freeing up cash for savings, investments, or breathing room. If your priority is paying off debt faster, you can choose a shorter term. There is no prepayment penalty, so you're not locked into a payment schedule that no longer fits your goals.
Getting there isn’t complicated. You can check your rate with a soft credit inquiry that won't affect your score3, view estimated monthly payments quickly, and get an approval decision in as little as 24 hours.4 There are no application fees, and loan amounts through BHG Financial go up to $250,0001, helping you address larger balances.
You've earned the income. Use it to reduce debt. Consolidating your debt through BHG Financial lets you take control, simplify your finances, and put yourself in a stronger position to build the future you're working for.
Maximize your cash flow
Explore fixed-payment personal loan options
Frequently asked questions (FAQs)
How long does it take until consolidation improves your cash flow?
You should see an improvement in your cash flow as soon as you’ve paid off your existing debts with the consolidation loan and replaced your multiple old payments with your new, lower payment. The exact impact on your cash flow depends on your loan amount, loan term, APR, and whether the lender makes payments directly to your creditors.
How long does debt consolidation take?
While the timeline for debt consolidation depends on the lender and the borrower’s situation, the process is often quick. For example, BHG Financial offers approval decisions in as little as 24 hours4 and funding in as few as five days.4 After you consolidate, the debt payoff timeline depends on the chosen term, which often runs from 2 to 10 years, depending on the lender.
Do consolidation loans hurt your credit score?
Initially, a consolidation loan can slightly reduce your credit score due to the hard inquiry required for the application and the new account, which reduces your average credit age. But over the long term, consolidating can help your credit score by lowering your credit utilization and making it easier to stay on top of your payments. Keeping your cards open even after consolidating the debt and making on-time payments is helpful.
Not all solutions, loan amounts, rates or terms are available in all states.
1 Terms subject to credit approval upon completion of an application. Loan sizes, interest rates, and loan terms vary based on the applicant's credit profile. Not all applicants will qualify for the lowest rate.
2 Personal Loan Repayment Example: A $60,000 personal loan with a 7-year term and an APR of 17.06% would require 84 monthly payments of $1,191.38.
3 There is no impact on your credit for applying. For personal loans, a complete credit history, which will appear as an inquiry on your credit report, will be performed upon acceptance and funding of the loan and may impact your credit.
4 This is not a guaranteed offer of credit and is subject to credit approval.
Consumer loans funded by Pinnacle Bank, a Tennessee bank, or County Bank. Equal Housing Lenders. 
For California Residents: Personal loans made or arranged pursuant to a California Financing Law license - Number 603G493.
Bankers Healthcare Group, LLC d/b/a BHG Financial NMLS ID# 2040829